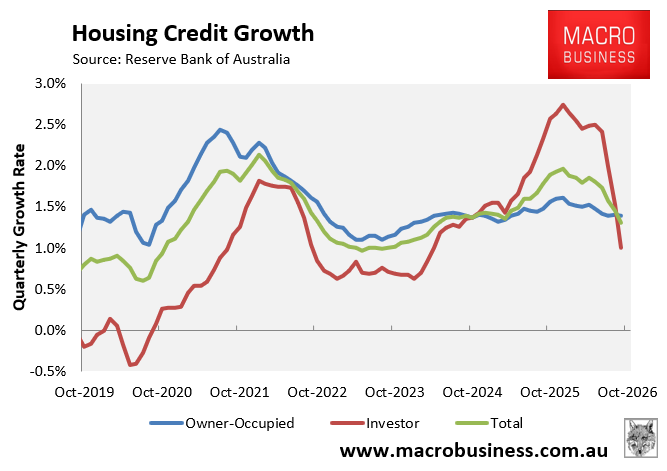
The recent federal budget changes to negative gearing and capital gains tax have sharply reduced investor credit growth.
The Reserve Bank of Australia’s (RBA) September credit aggregates data reported monthly investor credit growth of only 0.24%, a sharp contraction from the recent peak of 0.96% in December 2025.
Quarterly investor credit growth was only 1.0%, down from the recent peak of 2.7% in December 2025, and is tracking at its lowest level since March 2024:
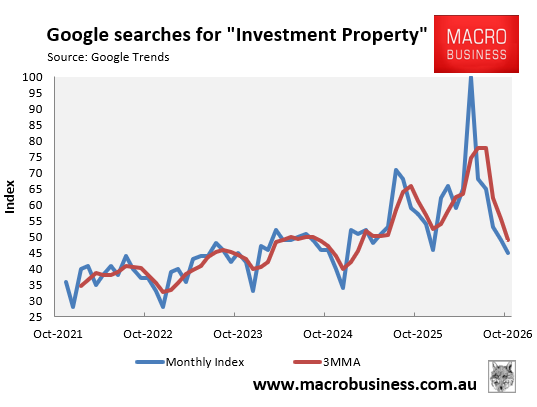
The decline in investor credit growth has broadly matched the sharp decline in Google searches for “investment property”:
The federal budget’s changes to negative gearing and capital gains tax have reduced investors’ borrowing capacity by around 30% because of lower after-tax cash flow.
As a result, investors now require higher rental yields for deals to stack up financially. And while gross rental yields have risen recently due to falling property prices and rising rents, they remain at low levels overall:
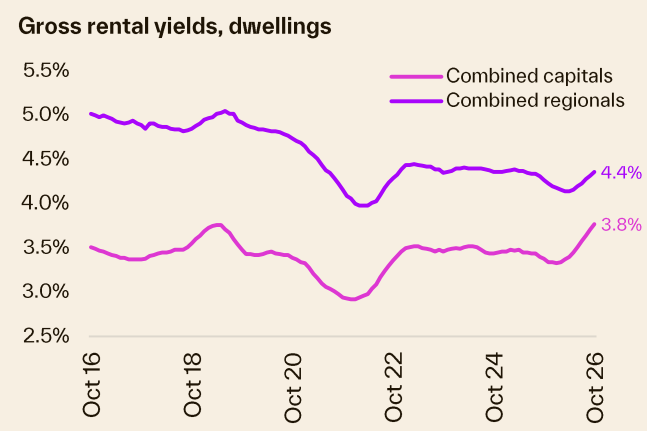
Source: Cotality
As illustrated above, the gross capital city rental yields of 3.8% compare poorly to a high-interest savings account at an Australian bank, where risk-free yields of more than 5% are available.
A property investor must also deduct maintenance, land taxes, mortgage interest, and other costs.
Moreover, with Australian dwelling values recording their sharpest decline in more than 40 years, already down 6.7% nationally since March, and more significant falls likely amid rising interest rates, the numbers no longer stack up for property investors.
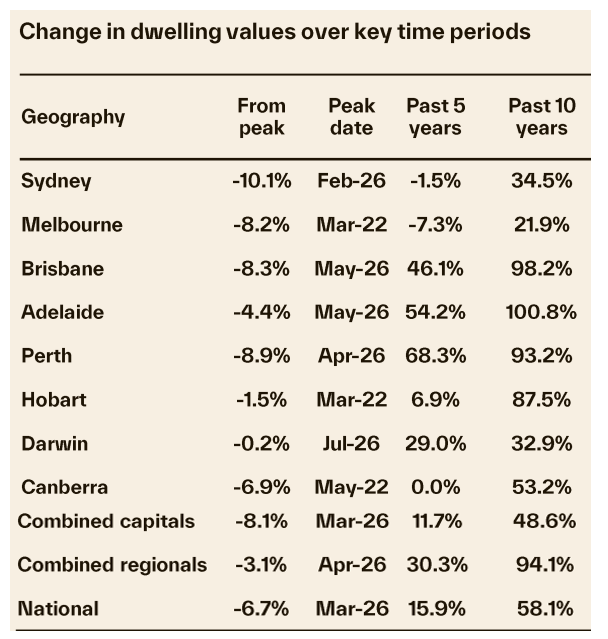
Decline from peak as of 31 October 2026 (Source: Cotality)
After all, with 5%-plus risk-free deposit rates available, there’s no reason to borrow into a declining market and take on negative cash flow.
A pro-cyclical factor is also at play. Investors have left the market because of the federal budget’s adjustments to negative gearing and the capital gains tax, which is one reason property values are declining. These declining housing values further reinforce the downward spiral by deterring investors from making purchases.
In the end, housing values need to reset lower and rental yields higher. And we are nowhere near the bottom.
