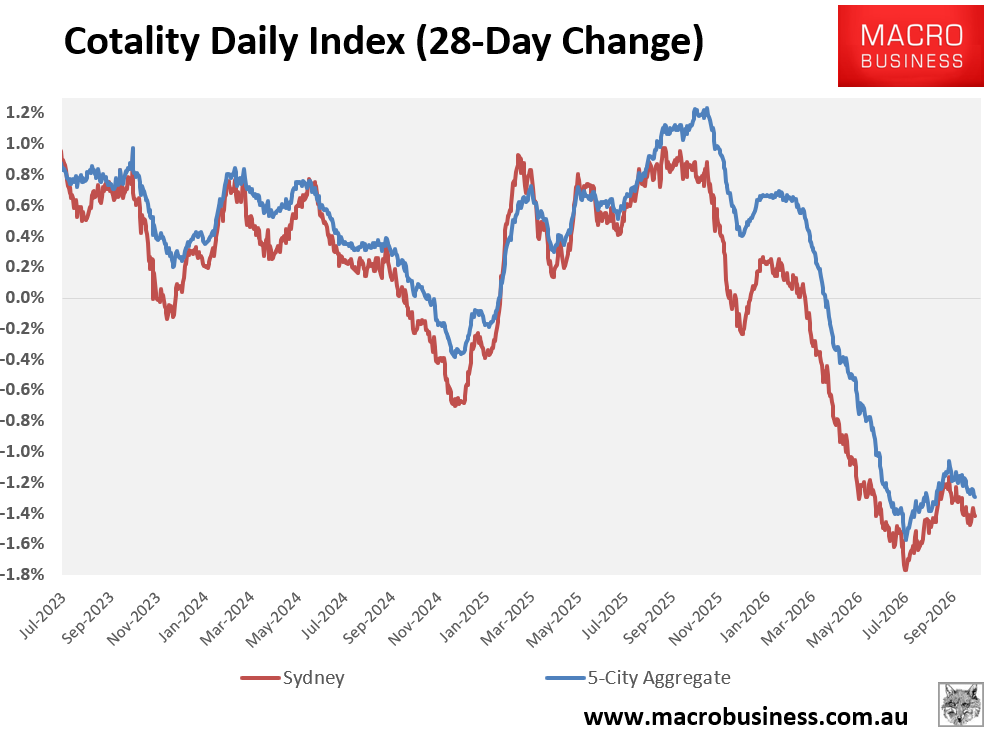
Sydney’s housing correction has reached a new milestone, with dwelling values down 10% from their 6 March 2026 peak, according to Cotality’s daily dwelling values index.
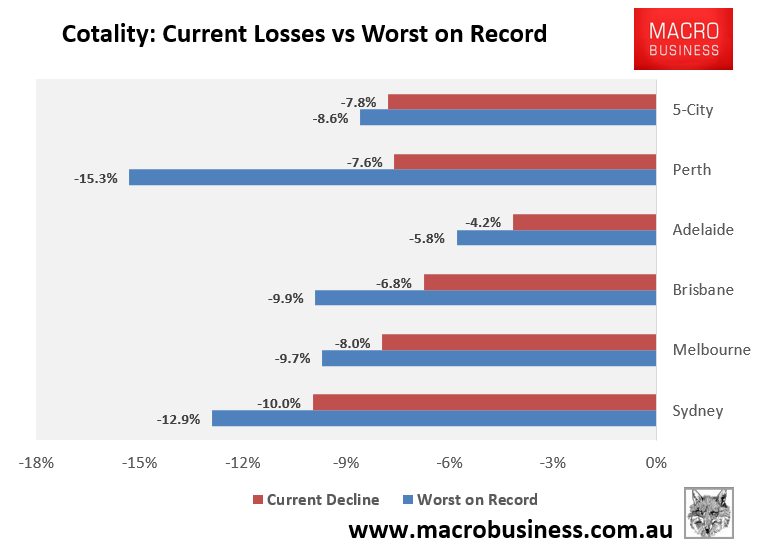
Sydney’s current decline of 10% ranks below the record 12.9% peak-to-trough fall recorded between June 2017 and May 2019, when the banking Royal Commission, APRA’s curbs on investor mortgage lending, and threats of a Shorten Labor government abolishing negative gearing hung over the market.
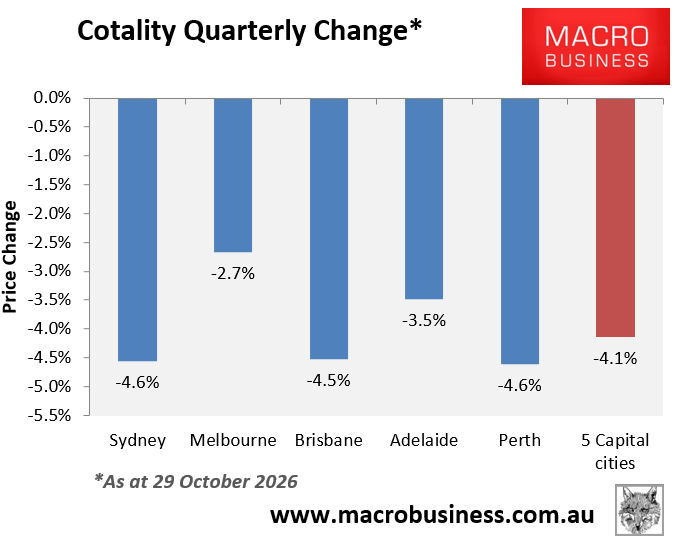
However, with Sydney dwelling values still falling 4.6% quarterly, they could break the record by the end of this year.
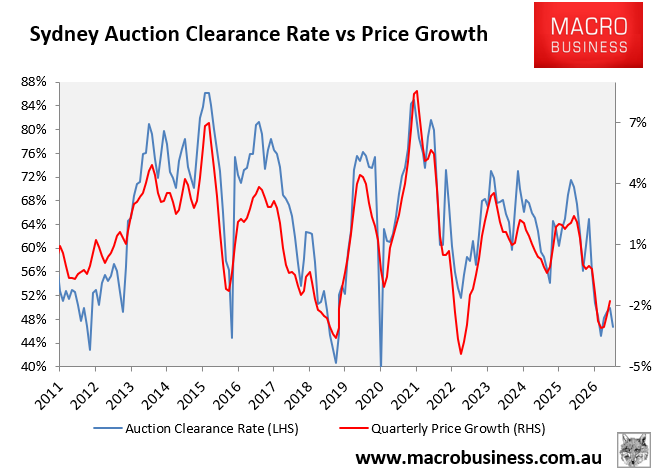
Indeed, the outlook for Sydney home prices looks grim. Monthly average auction clearance rates have fallen back below 50% so far in October as buyer enthusiasm has evaporated.
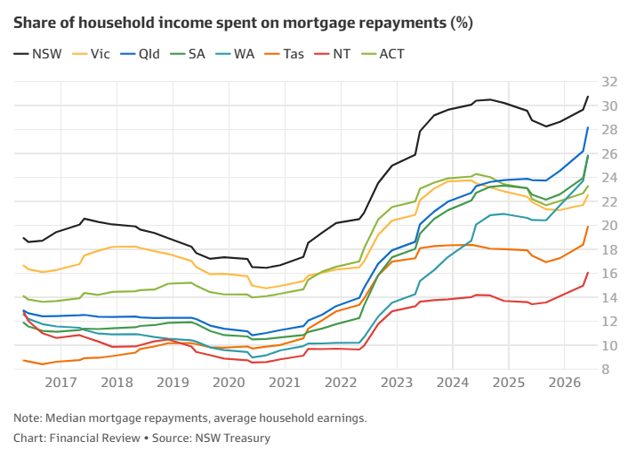
Last month’s Reserve Bank interest rate hike, and the likely follow-up next month, will also hit Sydney disproportionately, given that it is the nation’s most expensive market and most sensitive to rate changes.
SQM Research managing director Louis Christopher described Sydney’s housing market as “extraordinarily weak” last weekend and tipped a 20% price decline for Sydney.
“In Sydney, the market’s in deep trouble”, Christopher said. “I think the final clearance rate is going to be the weakest recorded this year”.
“You’ve got a lot of vendors out there who are not willing to budge yet. They’re not willing yet to meet the buyers. But the issue is that the buyers have taken a further step back, no doubt as a result of heightened concerns about yet another interest rate rise”.
“On this current tempo, we couldn’t rule out a 20% decline [in prices] from peak to trough in Sydney. It is that bad at this time”, he said.
This suggests Sydney’s housing correction may be only halfway through, with another 10% decline possible by mid-2027.
As illustrated in the table below, more than 28,000 first-home buyers in New South Wales have taken up the federal government’s 5% deposit scheme since 1 October 2025:
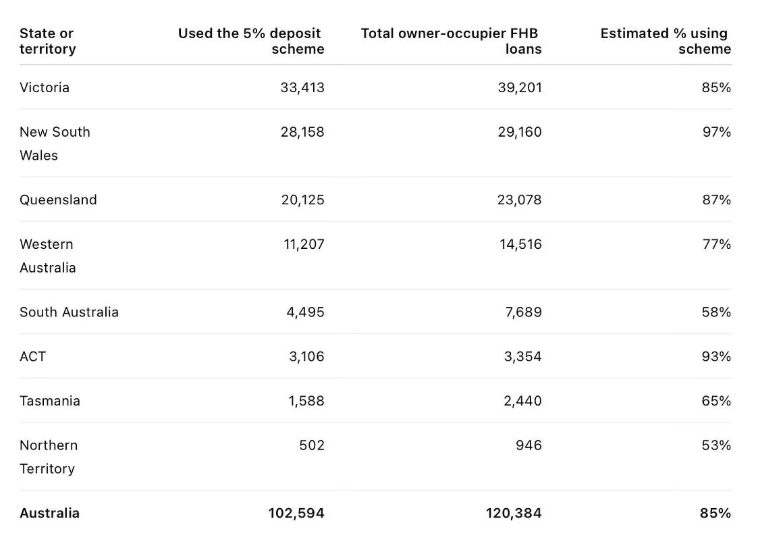
Users of the 5% first home buyer deposit scheme
Given the magnitude of price falls and the sharp rise in mortgage rates, many of these first-home buyers now face negative equity and severe mortgage stress.
