Mortgage stress and negative equity pressure young Australians
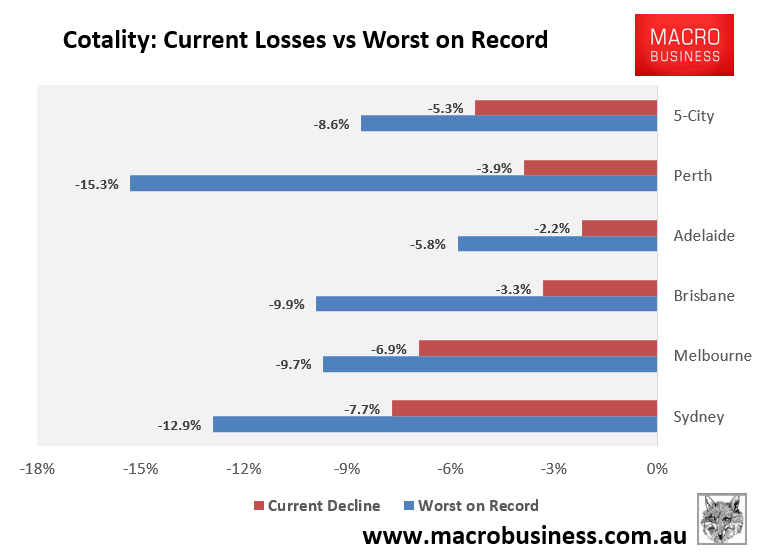
Cotality’s daily dwelling values index shows that dwelling values have declined by 5.3% from their 10 April peak across the five major capitals, led by Sydney (-7.7%) and Melbourne (-6.9%):
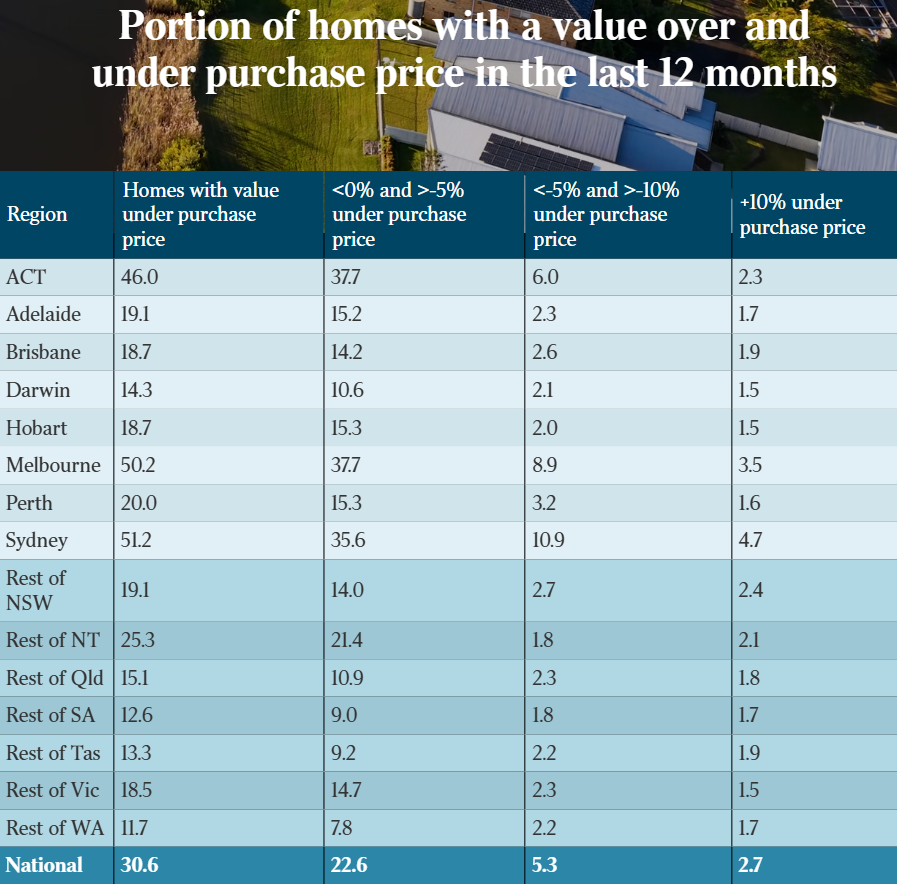
New analysis from Cotality shows that one in two homes purchased in Sydney and Melbourne in the past 12 months now sell for less than their purchase price.
Nationally, one in three homes purchased nationally since August 2025 would sell for less today.
Source: Cotality via The Australian
As illustrated above, the breakdown of losses nationally is as follows:
- 20% of recent buyers are down up to 5%
- 5.3% are down 5–10%
- 2.7% are down more than 10%
In Sydney, 10.9% of homes purchased in the past 12 months have lost between 5% and 10% of their value, with 4.7% losing more than 10%.
In Melbourne, 8.9% of homes purchased in the past 12 months have lost between 5% and 10% of their value, with 3.5% losing more than 10%.
HSBC has forecast a 13% peak-to-trough decline in home values across the combined capital cities, whereas CBA and Macquarie both tip falls of 10%.
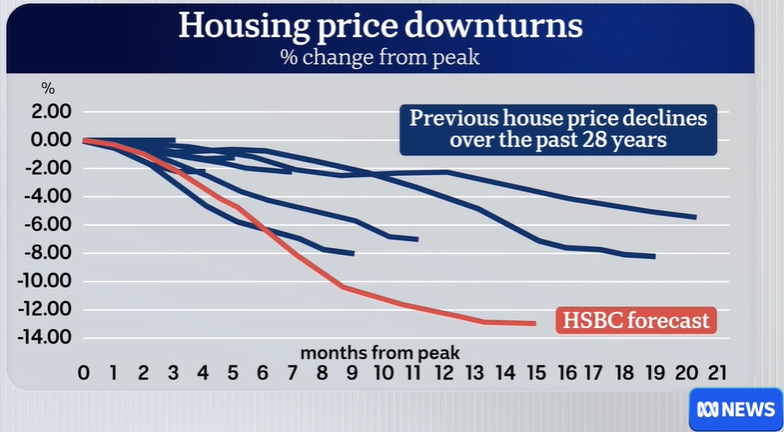
Chart from Alan Kohler (ABC)
First‑home buyers who purchased using the 5% deposit Home Guarantee Scheme are especially exposed.
Independent property analyst Cameron Kusher summarised the situation in the following statement:
“You’ve encouraged first‑home buyers into the market, then made tax changes which weakened it”.
At the same time, mortgage stress is already tracking at its highest level since the Global Financial Crisis in 2008:
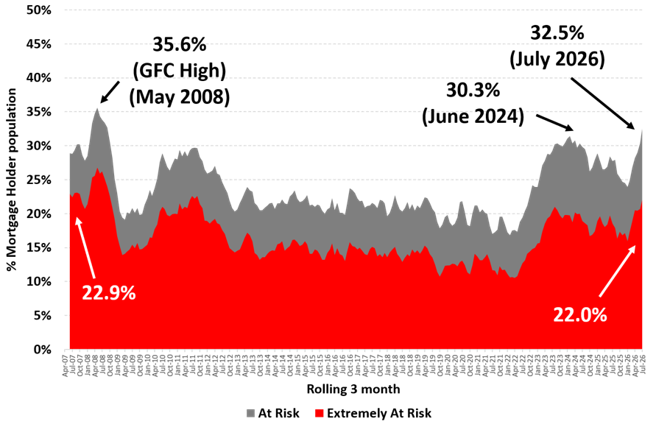
Chart from Roy Morgan Research
With financial markets now fully pricing in an additional two 25bp interest rate hikes, and the mortgage repayment burden already at its highest level since the early 1990s, when interest rates hit 17%, recent first-home buyers face intense mortgage stress alongside negative equity.
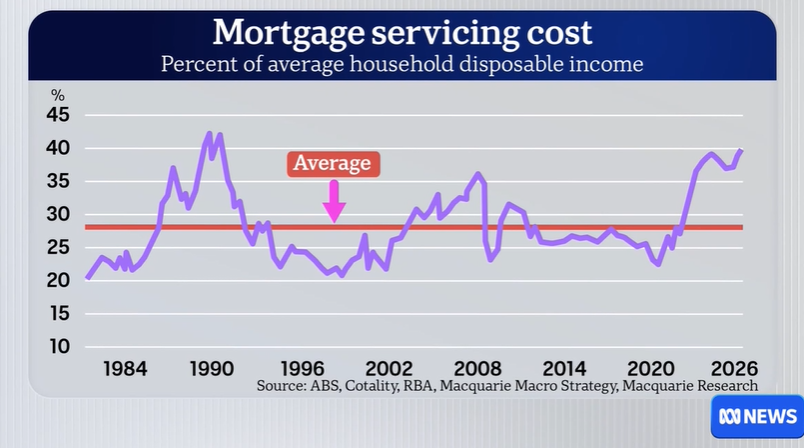
Chart from Alan Kohler (ABC)
Sebastian Watkins, CEO of Aussie Home Loans, added that many recent first-home buyers will become trapped in “mortgage prison” and unable to refinance to cheaper rates.
“The mortgage costs more than the house is worth. That’s a terrible outcome for first‑home buyers”, Watkins told The Australian newspaper.
“They’re now locked into that mortgage… they can’t even take advantage of the cheaper rates”.
The bottom line is that a significant share of recent buyers — especially first‑home buyers — are now stuck in mortgages they cannot refinance, with falling prices eroding equity and rising rates increasing repayment pressure.
Many were suckered into the market by the Albanese government’s expanded 5% deposit scheme, only to have the rug pulled out from under them by changes to negative gearing and capital gains tax, which have exacerbated the downturn.
