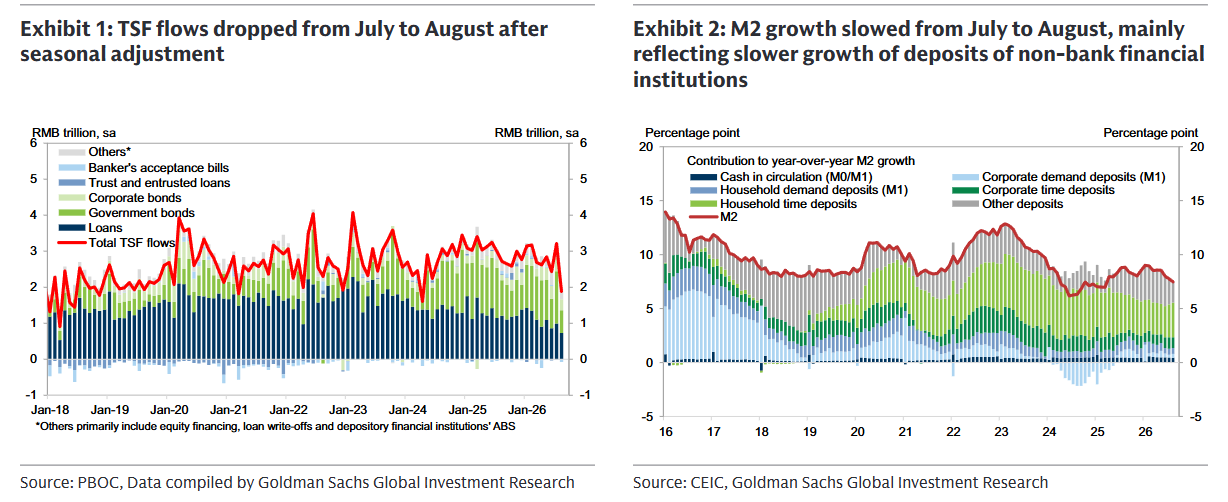
New yuan loans for August were out Monday and slowed sharply.
Bank loans of RMB 300bn missed the Bloomberg consensus of RMB 404bn.
Total social financing was RMB 1660bn, versus Bloomberg’s consensus of RMB 2122 billion.
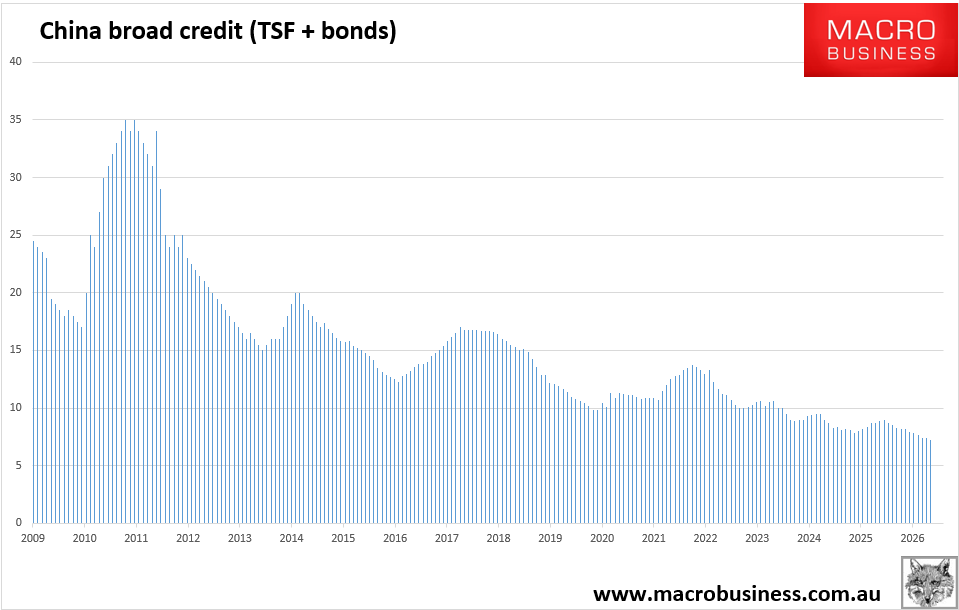
TSF stock growth (or Broad Credit, as I call it) was 7.2% year over year in August compared to 7.4% in July.
M2 was 7.5% year on year in August.
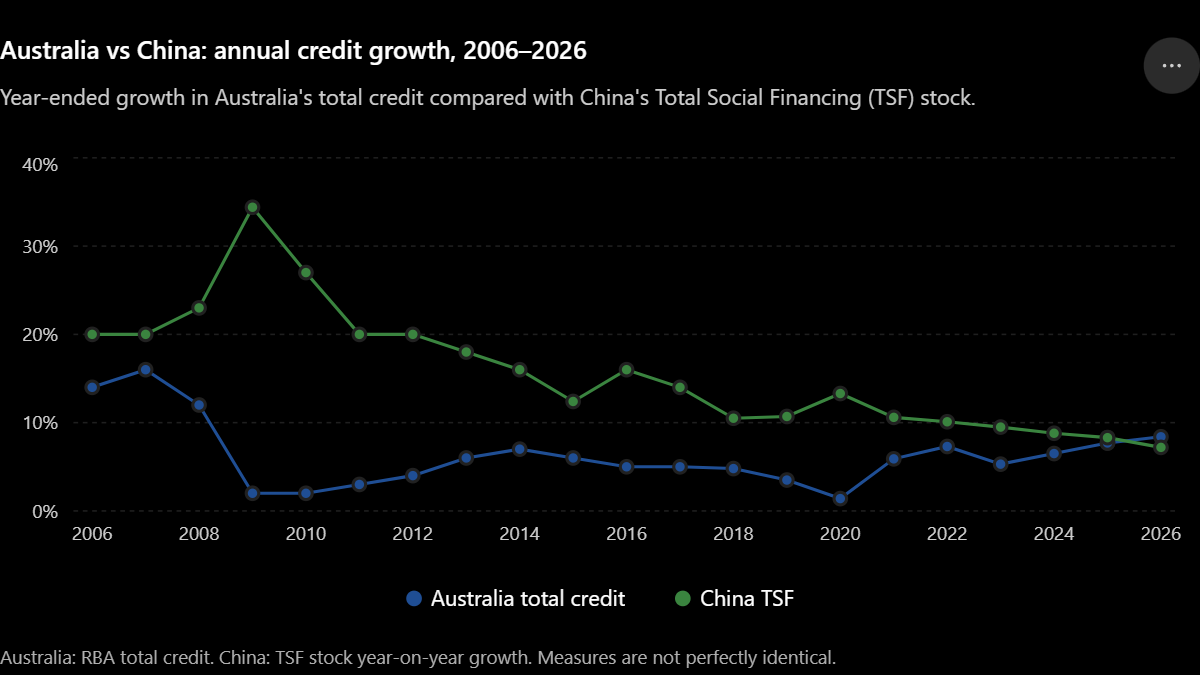
Interestingly, 2026 is turning out to be the year when China’s wasteful credit falls below Australia’s.
Given that China’s emerging-market economy still has far more productive uses for debt than Australia’s, what does that say about our credit allocation? Nothing good!
Back to China, here is the broad credit chart indicating lower growth ahead.
Iron ore is still falling in response.
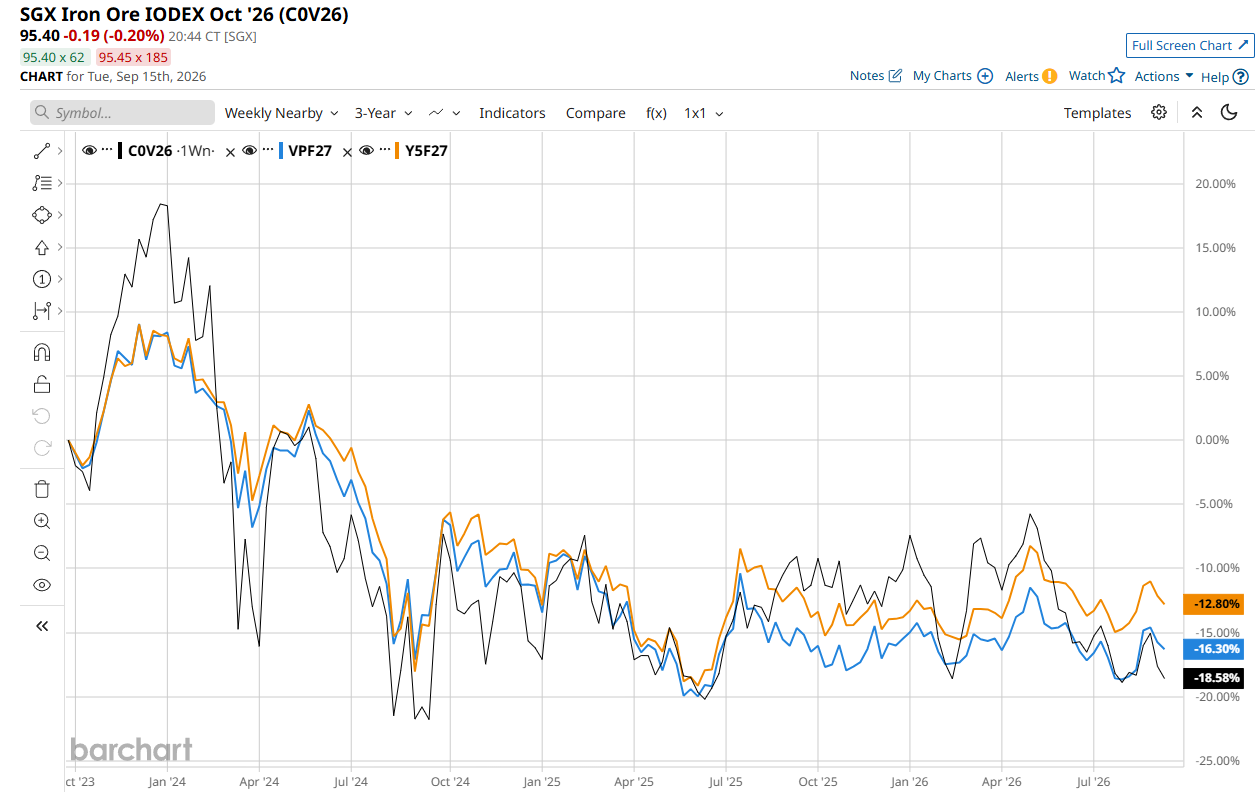
The cost of shipping from the Pilbara to China (C5) fell back a little on Monday to around $18/t, so we are now looking at an FOB iron ore price of about $77 per tonne or $85 CFR normalised.
This reflects a combination of weaker Chinese demand, the Pilbara killer ramp-up, and cockroach liquidation.
My latest forecast for the Pilbara killer is, if anything, more aggressive.
Media reports suggest the delivery and circulation (not necessarily commissioning) of 26 locomotives, which is enough to traffic roughly 50mt to port annually.
We’re seeing that in shipping numbers as well. The following chart blends MySteel and Guinea’s Bureau for the Evaluation of Quantities of Mining Products (BEQMP) numbers with my view of the post-rainy-season ramp-up for the remainder of the year.
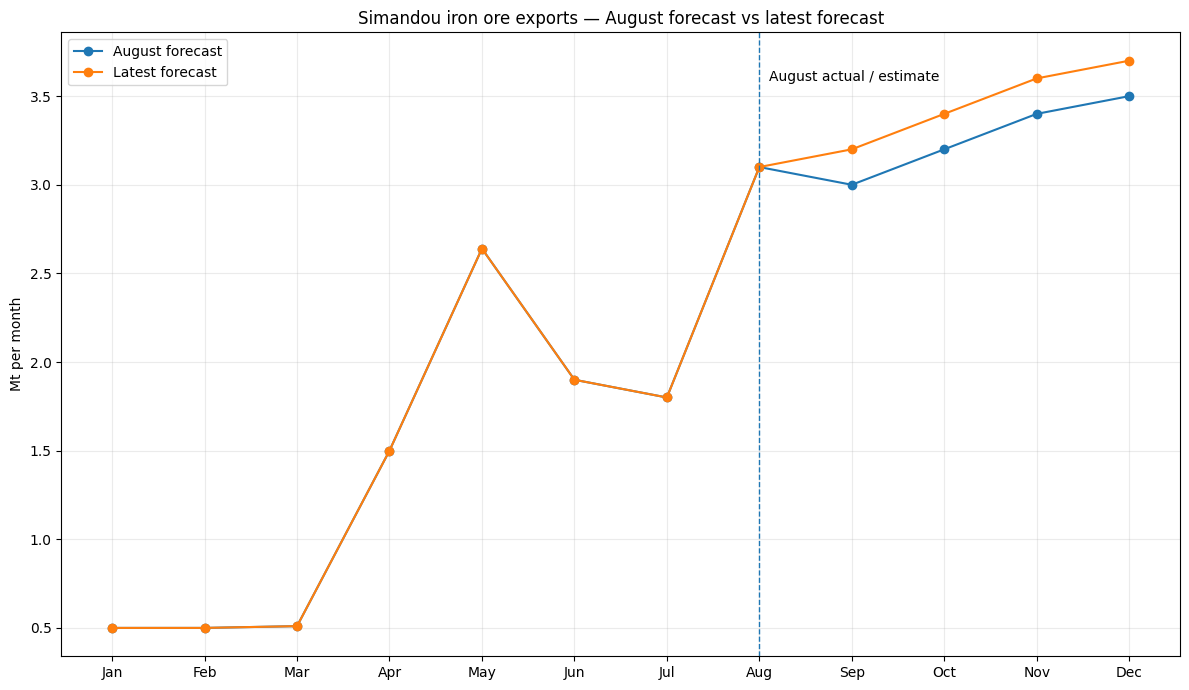
My flow forecast of 40mt by year-end 2026 appears to be on track.
I estimate that this flow rate will reach 70mt annualised by year-end 2027 and 100mt+ by year-end 2028.
As Chinese demand will keep falling 3% per year for the foreseeable future, the iron ore cost curve has likely just begun to crash.
