Credit Agricole with some useful analysis of the US dollar.
USD: the ‘USD smile’ revisited. The struggle of global central banks against inflation continues and this has recently triggered a renewed tightening of global financial conditions. At the same time, we have also seen a renewed improvement of global economic data that reflected the recent drop in global energy prices and the post-Covid reopening of the Chinese economy as well as the tightness of global labour markets that continues to fuel wage growth in a boost to household demand. All this kept market hopes for a soft landing in place. Moreover, some clients have started talking about a ‘no landing’ believing that a recession would be avoided altogether. Our own macro view remains that several
European and North American economies could come very close to slipping into a recession in coming months in response to continuing aggressive monetary tightening that has already hurt the US and UK housing markets as well as the Eurozone lending channel. We also believe that the deteriorating earnings outlook would slow down business hiring and investment from here. We think that investors are becoming somewhat complacent about the risks ahead.
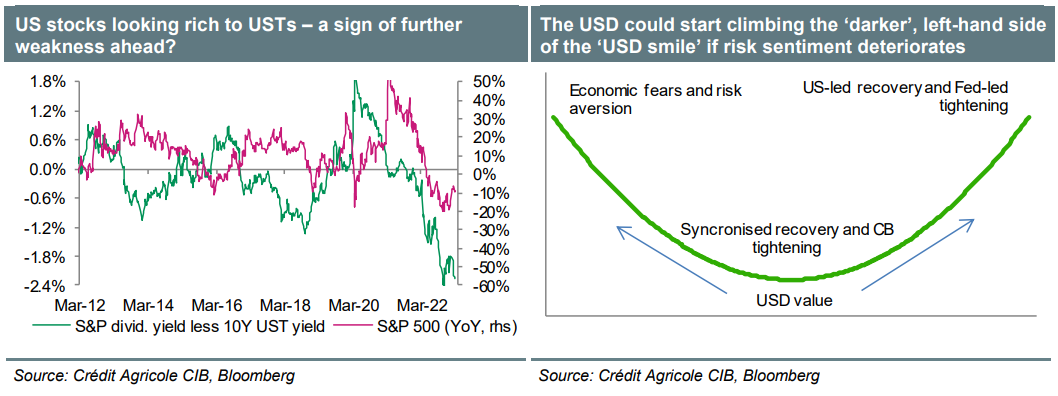
The recent macroeconomic developments have revived the ‘USD-smile’ as the growing Fed hike expectations boosted the rate appeal of King USD. In the near term, focus will be on the testimony of Fed Chair Jerome Powell at the US congress on 7 March as well as the February Non-farm payrolls as investors reassess the prospects for even more aggressive Fed tightening from here. That said, the fact that other central banks are tightening in tandem with the Fed could to dampen the positive impact on the currency, however. We therefore see a potential deterioration in risk sentiment on the back of a renewed worsening of the global outlook as the key support for the USD in coming months.
The full text of this article is available to MacroBusiness subscribers
