
Yesterday while delivering a speech about their bank’s bumper profit Ralph Norris and David Craig made some interesting statements.
Firstly on interest rates:
Commonwealth Bank chief executive Ralph Norris has declared official interest rates in Australia are unlikely to fall while inflation remains high, despite financial markets aggressively speculating the Reserve Bank will slash the official cash rate.
In his final results briefing, Mr Norris today said the Australian economy remained in good shape, especially compared to the rest of the world. However, he said negative perceptions of the economy that differed from “reality” were pushing down business and consumer sentiment sentiment across the nation.
“I think interest rates are unlikely to be reduced,” Mr Norris said.
“We have had lots of volatility but if you look at the Australian economy and inflation, inflation is above the RBA’s management bracket.
“In that context I don’t think we are going to end up far away from where rates are.”
I am not surprised by these statements from a bank chief, he obviously a member of the bullhawk clan.But if he is correct then he is predicting stagnant lending to continue for the foreseeable future:
The futures market is tipping the RBA is certain to cut rates at its September meeting. It also forecasts there could be seven reductions of 25 basis points by this time next year.
Mr Norris’s comments came after the bank posted a record $6.84 billion full-year profit, and moved to hose down international investors’ fears a national housing bubble has formed.
The hosing down obviously isn’t working because Mr Norris feels compelled to mention it yet again:
The bank’s outgoing chief executive, Ralph Norris, said the bank faced a tough environment with the fresh volatility on financial markets prompted by the fragile US and European sovereign debt crises.
“It’s a somewhat challenging environment, you only have to look at the last 24 hours to see that,” Mr Norris said.
CBA’s chief financial officer, David Craig, rejected concerns among international investors that the Australian banks hold too much exposure to a domestic residential property market which, the hedge funds claimed, was on the verge of overheating.
I am not sure that “overheating” is the word I would use to describe it, more like a slow melt at this stage. But with house prices falling and credit very subdued there is definitely an elevated level of risk associated with funding Australian banks at this stage. Not that you would perceive that risk from CBA’s current position:
Mr Craig said the bank’s mortgage book was worth $330 billion and in the past year had made writedowns of just $67m.
The Australian banks have been aggressively shorted over the past few months by overseas investors, especially hedge funds, speculating there was a property bubble emerging.
The CBA writedowns were the equivalent of 2 basis points of the bank’s lending book.
“$67 million is the smallest loss we have had on this (mortgage) book, it’s the safest part of our (entire) book,” Mr Craig told analysts.
As I have stated previously:
A slower growth environment is very much the thing that is going to test whether the bank’s equity-to-asset ratios can actually support their loan books…. it is not until we see debt growth fall back to a more sustainable level, that is in line with wages, that we can really measure the stability of the economy.
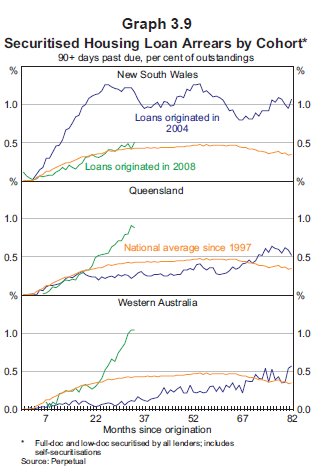
Given that Mr Norris is expecting interest rates to stay near or at their current level it is to be expected that credit issuance will continue to be subdued. Under these circumstances I would expect to see bank’s loan books to start coming under pressure over the next earnings season. It is yet to be seen if that is the case, however the sharply rising arrears of the 2008 cohort in Queensland and Western Australia in the latest SoMP suggest that there is certainly reason to be concerned:
Those sentiments were reflected yesterday by Fitch Ratings in their update of Australian RBMS rating criteria:
Fitch Ratings-Sydney-10 August 2011: Fitch Ratings has updated its Australian RMBS rating criteria as an addendum to the Asia-Pacific (APAC) Residential Mortgage Criteria. These criteria follow the release of an exposure draft published in June 2011 which outlined proposed changes to the Australian RMBS criteria.
The updated criteria, which is in line with the exposure draft, includes these changes: increased base default probability for both conforming and non-conforming loans; increased debt-to-income adjustments; reduced seasoning credits; one market value decline assumption for all states of Australia; increased probability of default for first home buyers; and the introduction of downward house price indexing if house prices show sustained downward price movements.
“The updated criteria reflect that the past decade has seen a significant change in the mortgage market, household leverage and a considerable increase in property prices. Those factors combined with the increased borrower sensitivity to interest rate rises may result in mortgage performance in any future downturn being significantly worse than the last recession,” said David Carroll, Director in Fitch’s Australian Structured Finance team.
“Fitch continues to maintain a Stable Outlook on the asset performance of the overall majority of Australian RMBS transactions and this updated criteria will continue to enhance the robustness of Fitch’s Australian RMBS ratings,” said Natasha Vojvodic, Head of Australian and New Zealand Structured Finance.
All Australian RMBS transactions will be reviewed by 10 February 2012. The impact of the “Global Criteria for Lenders’ Mortgage Insurance in RMBS” will be considered at the same time. Fitch expects the criteria to have a limited impact on existing, seasoned Australian RMBS transaction ratings due to the structural build-up of credit enhancement over time, subject to individual deal performance. The transactions most likely to be affected by the proposed criteria will be those issued more recently or which feature a pro-rata payment structure with low subordination or with ongoing revolving periods. Issuers will have the opportunity to indicate whether they intend to make any amendments to the transactions if the criteria changes impact existing ratings. Fitch will consider any proposed transaction amendment before any rating actions are taken.
It will be interesting to see how overseas investors interpret that update.